FHA Title I Home Improvement Loan: Preparing Application Records
Advertisements
An FHA Title I Home Improvement Loan can help eligible borrowers finance repairs and improvements that make a property more functional, useful, or livable. Understanding the application process is essential for anyone considering this type of financing in 2026.
Preparing financial records, property information, and renovation estimates before contacting a lender can make the application process more organized. However, there is no single federal checklist requiring exactly seven identical documents from every applicant.
This guide explains seven important documentation categories that borrowers may need to prepare, along with loan limits, eligibility considerations, and practical steps for discussing an application with a HUD-approved Title I lender.
Understanding the FHA Title I Home Improvement Loan Framework
The FHA Title I Home Improvement Loan program supports eligible property repairs, alterations, and improvements through loans issued by participating private lenders and insured by the Federal Housing Administration.
Unlike a grant, this financing must be repaid according to the loan agreement. FHA insurance protects the lender against certain losses; it does not eliminate the borrower's obligation to repay the debt.
For eligible single-family properties, the general maximum loan amount is $25,000. Loans exceeding $7,500 must generally be secured by a lien on the property, while loan amounts and requirements vary for other property types.
The Importance of Meticulous Documentation for Loan Approval
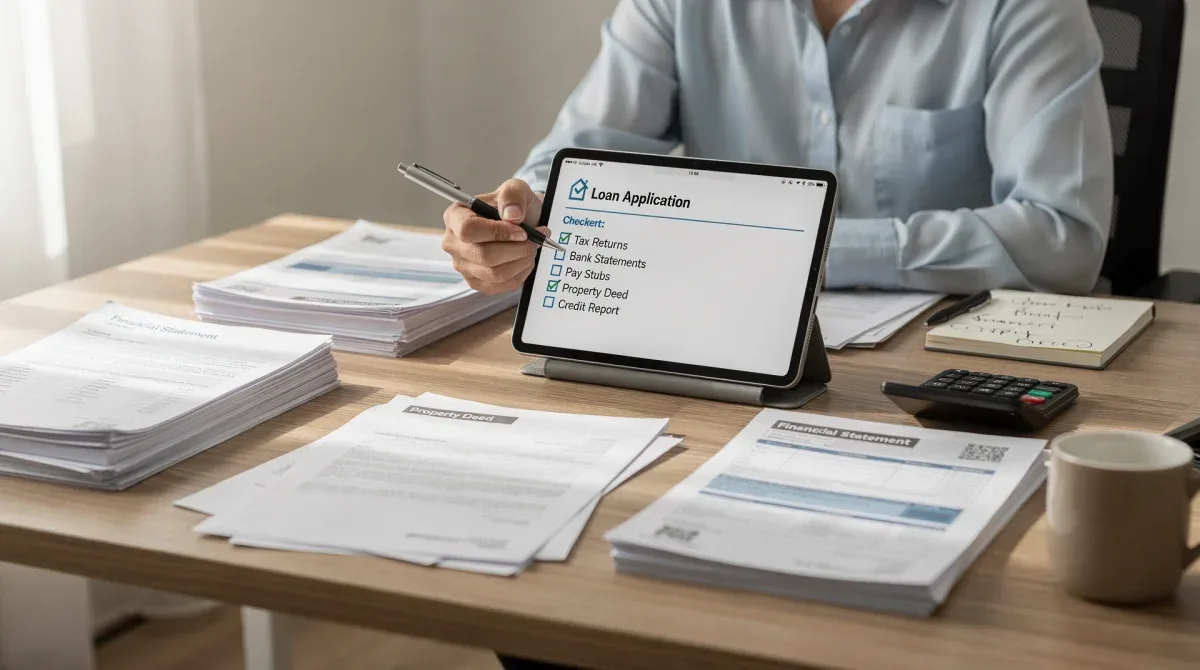
Accurate documentation helps lenders evaluate whether an applicant qualifies for an FHA Title I Home Improvement Loan and whether the proposed renovation meets applicable program requirements.
The application process can involve verifying repayment capacity, identifying the borrower's legal interest in the property, and reviewing the intended use of loan proceeds.
Organizing these materials before submitting a loan application can reduce confusion and help borrowers respond promptly when additional information is requested.
Why Documentation Accuracy Matters
Financial institutions rely on application records to verify important information about the borrower, property, and proposed improvements. Inaccurate documents can lead to additional questions or delays.
Applicants should ensure that names, addresses, income figures, and project estimates are consistent across submitted materials. Any relevant differences should be explained accurately rather than concealed.
For an FHA Title I Home Improvement Loan, providing complete and truthful information is particularly important because participating lenders must follow federal program requirements and evaluate repayment risk.
Verification: Accurate records help lenders confirm eligibility information.
Consistency: Matching financial and property details reduces unnecessary questions.
Compliance: Truthful documentation supports responsible lending decisions.
Impact of Incomplete Records on Loan Processing
Missing records can interrupt an application when the lender cannot confirm information necessary to make a credit decision or verify the intended renovation.
However, required documentation can differ among lenders and borrowers. A self-employed applicant may need different income records than an employee, while property-related requirements depend on the applicant's legal interest.
Preparing for an FHA Title I Home Improvement Loan therefore means asking the participating lender for its specific checklist instead of assuming that every applicant must provide the same documents.
Additional Requests: Missing information may require follow-up documents.
Processing Delays: Verification cannot always proceed until records are complete.
Application Decisions: Approval depends on eligibility and underwriting, not paperwork alone.
Mandatory Record 1: Proof of Income and Employment
Income verification is an important part of evaluating an FHA Title I Home Improvement Loan because lenders must assess whether the borrower has a reasonable ability to repay the proposed debt.
Depending on employment circumstances, this may involve recent pay statements, employer information, tax documents, or other acceptable evidence of income.
Borrowers should prepare records that accurately represent their current financial situation. The exact documents and reporting periods depend on the lender's verification procedures and applicable underwriting requirements.
Required Income Documentation
Employed borrowers may be asked to provide recent pay stubs, W-2 forms, or employment verification. These records help establish earnings and clarify whether income is reasonably stable.
Self-employed applicants may need tax returns, business income records, or other documentation sufficient to demonstrate repayment capacity. Requirements should be confirmed directly with the lender.
Keeping relevant materials organized can simplify the application process, although practices used for federal grants should not be confused with the underwriting requirements of an FHA-insured loan.
Mandatory Record 2: Property Ownership and Deed Information
Applicants generally need to demonstrate an eligible legal interest in the property receiving improvements. For many homeowners, a property deed or other acceptable ownership evidence can support this requirement.
However, an FHA Title I Home Improvement Loan is not necessarily limited to people holding traditional fee-simple ownership. Certain eligible leasehold interests and recorded land installment contracts may also qualify under federal rules.
Borrowers should provide information about their legal interest and any existing liens when requested. Loans exceeding the applicable unsecured threshold may require documentation for establishing the necessary property lien.
Mandatory Record 3: Detailed Home Improvement Project Plan
A renovation plan helps lenders determine whether proposed improvements are eligible and whether the requested loan amount corresponds to the project's costs.
For an FHA Title I Home Improvement Loan, the description should identify the intended work, expected materials, and estimated expenses. Projects may include qualifying repairs to plumbing, heating, roofing, or other property systems.
When a contractor or dealer will perform the improvements, the lender must obtain an appropriate proposal or contract describing the work and its estimated or actual cost. Borrowers performing eligible work themselves may face different documentation and financing conditions.
Mandatory Record 4: Current Mortgage Statements and Financial Liabilities
Existing debts affect a borrower's ability to manage additional monthly payments. Lenders review financial obligations when assessing repayment capacity and determining whether a proposed loan is appropriate.
For an FHA Title I Home Improvement Loan, applicants may be asked to provide current mortgage information, details of installment loans, or explanations of other significant financial commitments.
Having an existing mortgage does not automatically prevent eligibility. However, the lender must evaluate the borrower's overall financial situation, and loans requiring property liens involve additional considerations.
Mandatory Record 5: Credit Report and History Authorization
Participating lenders evaluate creditworthiness as part of the federal Title I lending process. Credit history can help identify existing obligations and previous repayment behavior.
Applicants should expect a credit review and may need to provide authorization or other information required by the lender. The federal rules also require a properly executed credit application and verification of identifying information.
Before applying for an FHA Title I Home Improvement Loan, borrowers can review their credit reports for inaccuracies and address relevant issues. However, a particular score does not guarantee approval or determine the interest rate by itself.
Mandatory Record 6: Bank Statements and Asset Verification
Some participating lenders may request bank statements or other financial records to clarify an applicant's resources, financial activity, or ability to meet repayment obligations.
However, applicants should not assume that every FHA Title I Home Improvement Loan requires two or three months of bank statements or a separate cash contribution toward the proposed project.
Federal program guidance generally does not require borrowers to contribute personal funds to eligible improvement costs. The lender should explain whether any asset verification or additional documentation is necessary for the specific application.
Mandatory Record 7: Identification and Residency Proof
Verifying identity helps lenders comply with applicable program requirements and reduce the risk of fraudulent applications.
Applicants should be prepared to present valid government-issued photo identification and provide accurate personal details. Additional address or residency information may be requested depending on the lender's procedures.
For an FHA Title I Home Improvement Loan, identity verification should be completed through the participating lender's established process. Borrowers should avoid sharing sensitive documents through unsolicited messages or unverified websites.
Key Document | Brief Description |
|---|---|
Income Proof | Records such as pay statements or tax documents may help establish repayment capacity. |
Property Deed | Ownership or other acceptable legal-interest records help demonstrate property eligibility. |
Project Plan | Descriptions, estimates, and applicable contractor proposals document intended improvements. |
Credit Report | Credit information supports the lender's review of existing obligations and repayment risk. |
Frequently Asked Questions About FHA Title I Loans
What is the maximum loan amount for an FHA Title I Home Improvement Loan?▼
The general maximum for an eligible single-family property improvement loan is $25,000. Other limits apply to multifamily properties, manufactured homes, and certain specialized improvement projects. Loans exceeding $7,500 generally require a property lien. The actual amount available depends on eligible improvement costs and lender approval.
Can I use an FHA Title I loan for luxury improvements?▼
FHA Title I financing is intended for eligible improvements that enhance a property's livability, usefulness, or functionality. Expenditures primarily intended for luxury or recreational purposes may not qualify. Borrowers should review their proposed improvements with a participating lender before assuming specific renovations are eligible.
Do I need good credit to qualify for an FHA Title I Home Improvement Loan?▼
Participating lenders must evaluate creditworthiness and repayment capacity. A strong credit history may support an application, but eligibility depends on the lender's underwriting assessment and applicable program requirements. No applicant should assume approval simply because a particular credit score has been achieved.
What if my property has an existing mortgage?▼
An existing mortgage does not automatically disqualify an applicant from receiving an FHA Title I Home Improvement Loan. The lender will consider financial obligations and applicable property requirements. For loans requiring a lien, the existing financing arrangement and available documentation may affect processing.
How long does the FHA Title I loan application process take?▼
There is no universal approval period that applies to every Title I lender. Processing depends on document verification, credit review, project eligibility, and the lender's procedures. Preparing the seven documentation categories described in this guide may help organize an application, but these categories are not an official universal list of mandatory records.
Next Steps for Your Home Improvement Journey
Preparing for an FHA Title I Home Improvement Loan begins with understanding the program's eligibility requirements, identifying appropriate renovation costs, and organizing financial and property information.
The FHA Title I property improvement program provides access to guidance about qualifying improvements, loan conditions, financing limits, and participating lenders.
Before signing an agreement, review the proposed interest rate, repayment schedule, finance charges, security requirements, and total cost of borrowing. Title I financing is not a grant, and repayment obligations remain in effect.
Borrowers may also explore broader housing assistance and application options while keeping the eligibility rules of separate programs distinct.
A practical next step is to contact a HUD-approved Title I lender, request its specific documentation checklist, and confirm whether the planned improvements qualify before committing to renovation expenses.